Around 1.2 billion young people in developing countries are expected to reach working age over the next 10 to 15 years, but only about 420 million jobs are projected to be created if current trends continue, highlighting a growing employment challenge for the global economy.
The World Bank Group and the International Monetary Fund (IMF) are calling for job creation to be placed at the centre of development strategies, with greater emphasis on private investment, infrastructure development and the use of technology to boost productivity.
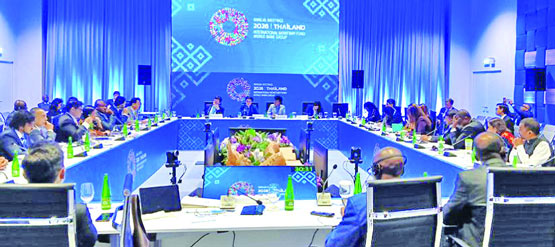
The 2026 annual meetings of the IMF and the World Bank Group began in Bangkok, Thailand, on October 12 and will continue until October 18. Finance ministers, central bank governors, policymakers, development partners and business leaders from around the world are attending the meetings.
Global economic growth, investment, financial stability, employment and the impact of artificial intelligence (AI) are among the key issues on the agenda.
The World Bank’s employment strategy stresses that economic growth alone is insufficient. Growth must translate into productive jobs that offer better wages, improved working conditions and opportunities for career advancement.
Achieving this will require sustained investment in infrastructure and human capital, a supportive business environment and the mobilisation of private capital for productive activities.
A widening employment gap
According to the World Bank, around 1.2 billion young people in developing countries will reach working age over the next 10 to 15 years. However, only about 420 million jobs are expected to be created during the same period if current trends persist.
The resulting gap underscores the scale of the challenge facing developing economies as they struggle to provide employment for a rapidly expanding workforce. Governments cannot address this challenge through public spending and employment programmes alone. The World Bank is highlighting the private sector’s role as a key driver of investment, entrepreneurship and job creation. Investment in electricity, transport, ports, urban infrastructure, education, healthcare and skills development will be essential to expanding productive employment. Governments must also ensure policy predictability, reduce unnecessary regulatory barriers and improve the business environment to encourage domestic and foreign investment.
AI presents opportunities and risks
The impact of AI has emerged as a major topic at the annual meetings, with policymakers and development leaders examining how the technology could help create more and better jobs while minimising disruption to the labour market. At a session titled “Small AI, More and Better Jobs” on October 12, World Bank Group President Ajay Banga, IMF Managing Director Kristalina Georgieva and Singapore President Tharman Shanmugaratnam discussed the potential of practical, affordable AI technologies to support development and employment in developing countries.
AI could improve productivity in agriculture, healthcare, education, business and entrepreneurship, enabling workers and small enterprises to accomplish more with limited resources. It could also help businesses improve efficiency, expand operations and develop new products and services.
However, the rapid adoption of AI could transform existing occupations, automate routine tasks and reduce opportunities for entry-level workers. Without adequate preparation, the technology could also widen the gap between workers with advanced digital skills and those with limited access to training and education.
According to the IMF, nearly 40 per cent of jobs worldwide could be affected by AI. This does not mean that all these jobs will disappear. In many occupations, AI is more likely to change how work is performed, automating some tasks while creating demand for new skills and potentially opening up new employment opportunities.
Preparing workers for these changes will be critical. Governments, educational institutions and businesses need to expand vocational training, reskilling programmes and digital education to help workers adapt to changing labour-market demands. The challenge is to ensure that technological progress improves productivity and creates opportunities rather than deepening unemployment and inequality.
Mobilising private capital
Mobilising private investment in developing economies is another major priority at the meetings.
A session titled “Mobilising Private Capital for Jobs”, scheduled for October 14, will focus on ways to reduce investment risks in emerging economies, expand local-currency financing, provide financial guarantees and introduce policy reforms to attract capital. The World Bank has identified three key areas for employment generation: investment in basic infrastructure and human capital, a predictable and supportive business environment, and the mobilisation of private capital on a large scale.
Progress in these areas could help expand employment in manufacturing, agribusiness, healthcare, tourism and other productive sectors, particularly those capable of generating higher-value goods and services.
For developing economies, attracting investment is not simply a matter of increasing the volume of capital entering the country. Investment must also generate sustainable employment, improve productivity and strengthen local businesses. Small and medium-sized enterprises are particularly important in this regard. Better access to finance, technology, infrastructure and markets could help them expand their operations and create jobs, including for young people and women.
Implications for Bangladesh
The discussions in Bangkok have particular significance for Bangladesh, where creating productive employment for young people remains a major economic priority. Diversifying export-oriented industries, attracting foreign investment and supporting small and medium-sized enterprises will be essential to expanding employment opportunities. Bangladesh needs to prepare its workforce for a labour market increasingly shaped by automation, AI and other digital technologies. Expanding technical education, digital skills training and job-oriented vocational programmes could help young people secure employment in emerging sectors while improving the competitiveness of existing industries. Closer cooperation between educational institutions and employers is also necessary to address the mismatch between the skills graduates acquire and those businesses require. Training programmes should be designed around actual labour-market demand, with greater emphasis on practical experience and industry-relevant skills.
Improving investor confidence, reducing barriers to doing business, upgrading power and transport infrastructure and expanding access to finance for women and young entrepreneurs could further support job creation.
Bangladesh must also ensure that technological change does not leave behind workers with limited education or digital skills. Affordable training, accessible digital infrastructure and support for small businesses could help spread the benefits of AI beyond large companies and major urban centres.
However, international discussions and financing commitments alone will not guarantee the creation of new jobs. Tangible results will depend on effective policies, accountability, the efficient use of investment and closer coordination between education, industrial development and labour-market needs.
The central message emerging from the IMF-World Bank annual meetings in Bangkok is that economic development must be judged not only by growth rates but also by the number, quality and sustainability of the jobs it generates.
With 1.2 billion young people expected to enter working age in developing countries over the next 10 to 15 years, creating productive employment will be one of the biggest tests facing policymakers. How governments, businesses and development institutions respond to this challenge will have far-reaching implications for economic growth, social stability and shared prosperity in the coming decade.